ABSTRACT
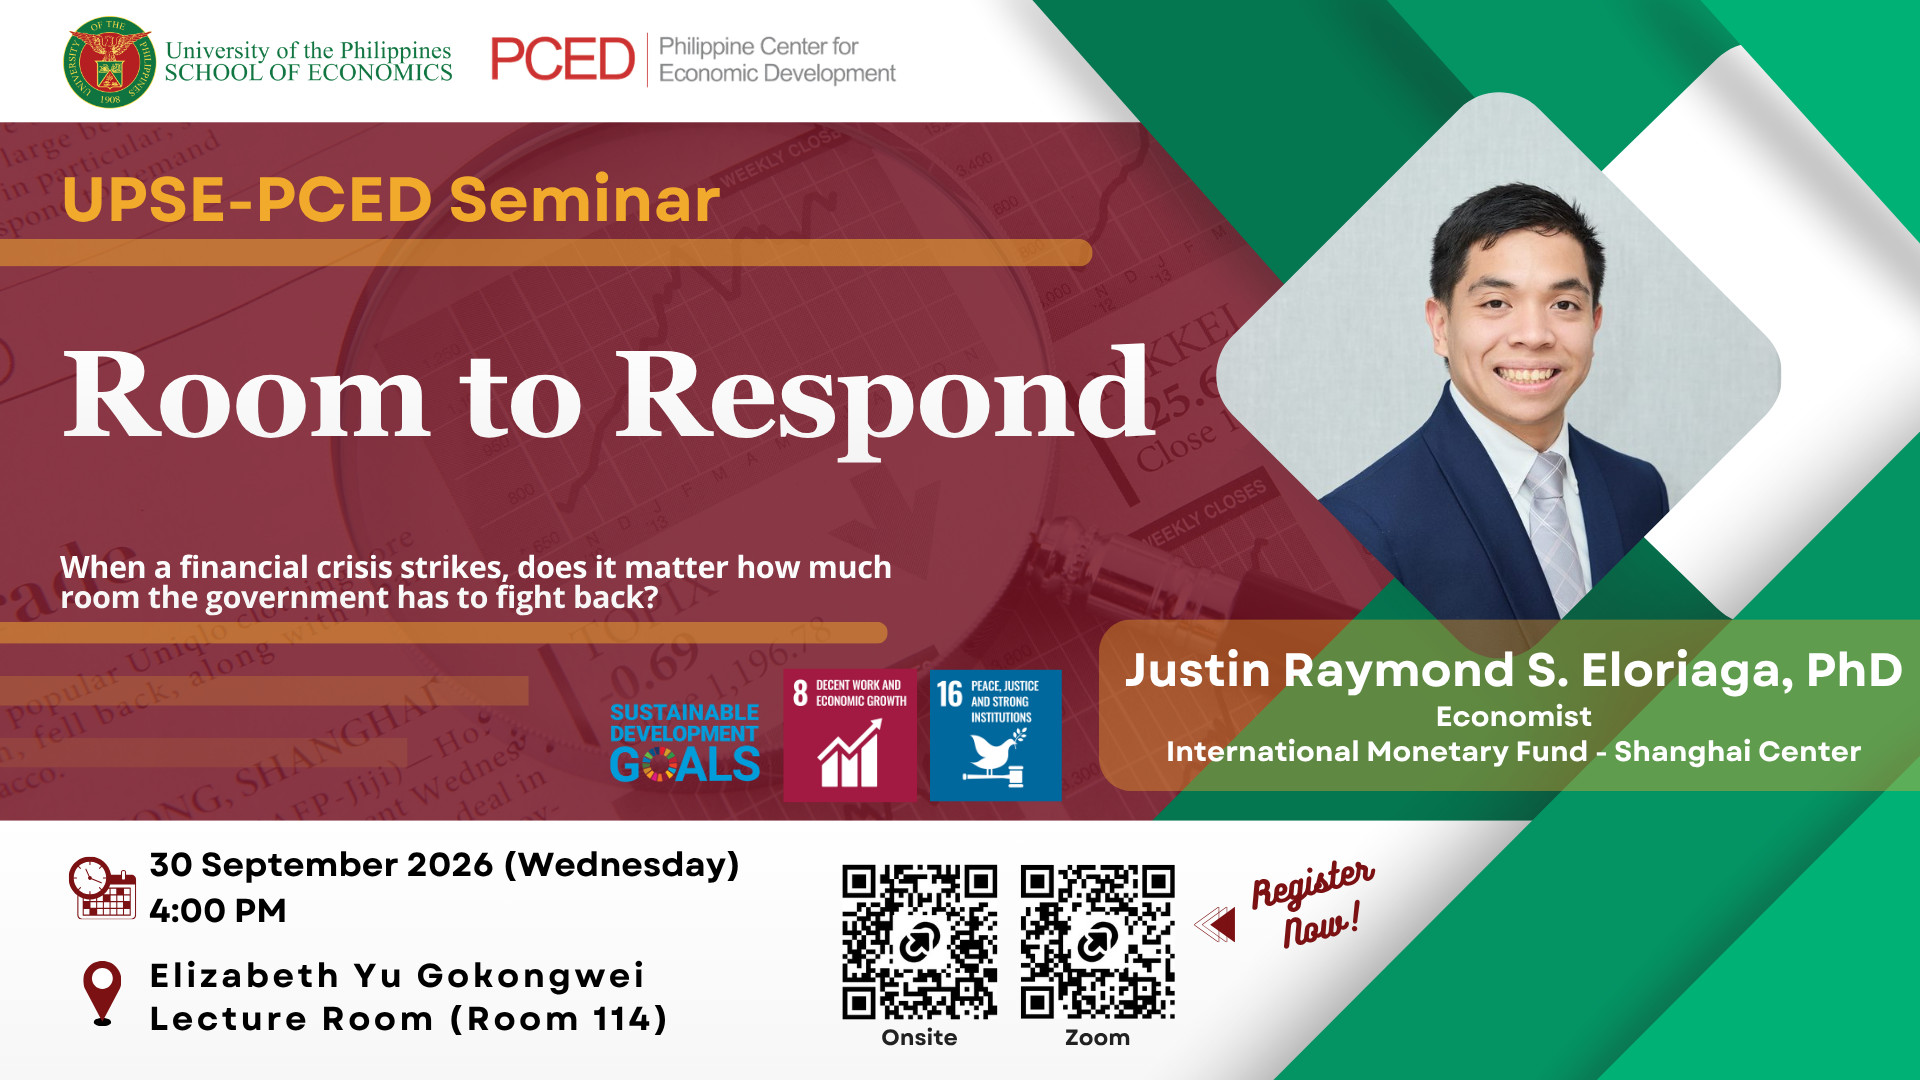
When a financial crisis strikes, governments with room to act are believed to escape with smaller recessions, and one number dominates the assessment of that room: the ratio of public debt to GDP. Across 140 systemic banking crises since 1976, we find the ratio matters less, and differently, than the advice assumes. It adds nothing to crisis prediction once credit-boom symptoms are accounted for, and its association with severity is narrow, concentrated in advanced economies at long horizons and above 90 percent of GDP, while in emerging market and developing economies the average penalty at those horizons is demonstrably small, though tail outcomes are estimated less precisely. What debt does predict, strongly, is the response. Advanced economies entering a crisis with one standard deviation more debt tightened their budgets by more than four percentage points of GDP relative to low-debt peers. We therefore construct two indices, the transparent Policy Buffers Index and the outcome-based Effective Space Index, which carry information the ratio alone does not.